Most registered businesses can apply for a multi-currency business account, including sole traders, partnerships, LLCs and corporations, but each provider sets its own rules. Eligibility depends on where the business is registered, its legal structure, its industry and whether its owners pass identity checks, including disclosure of anyone who owns 25% or more.
Key Takeaways
- Eligibility for a multi-currency business account is set by each provider, not by a single law, so a business accepted by one provider can be refused by another.
- Providers commonly ask for registration documents, a tax ID, a business address and details of beneficial owners; in the US, the FinCEN customer due diligence rule covers anyone who owns 25% or more of a legal entity.
- Industry matters: Wise, for example, does not support businesses involved in cryptocurrency, tobacco or adult content, or companies with bearer shares.
- Setup costs vary: as of September 2026, Wise says US business accounts are free to open, with a one-time 31 USD fee to receive payments, and UK businesses pay a one-time fee of £50 for all features.
In today’s globalized marketplace, multi-currency business accounts have become invaluable tools for companies seeking to navigate international operations. These accounts let a business hold, receive and pay out several currencies from one account, which can reduce how often money has to be converted. But what types of businesses are eligible to open a multi-currency business account? Let’s explore the diverse range of entities that fall under this category.
Businesses of many sizes can apply for multi-currency accounts, from startups and small enterprises to large multinational corporations, but each provider decides who qualifies based on the country of registration, the legal structure, the industry and the result of identity checks. Whether you’re a sole proprietorship, a partnership, a limited liability company (LLC), or a corporation, many providers accept your structure, although not every provider accepts every structure. For example, as of September 2026 Wise does not accept UK trusts or Scottish Limited Partnerships.
For startups and small businesses venturing into the global marketplace, multi-currency accounts serve as indispensable tools for establishing an international presence and facilitating cross-border transactions. By opening a multi-currency account, startups can seamlessly manage finances in different currencies, mitigate the complexities associated with currency fluctuations, and enhance their competitiveness in international markets.
Medium-sized enterprises looking to expand their operations globally can also benefit from multi-currency accounts. These accounts provide the flexibility and scalability needed to support complex financial transactions, such as cross-border payments, currency hedging, and treasury management. By consolidating their international banking activities into a single multi-currency account, medium-sized enterprises can streamline operations, optimize cash flow, and reduce administrative overhead.
Large corporations with extensive global footprints can leverage multi-currency accounts to centralize control over their international finances and streamline currency management. These accounts offer advanced features and capabilities tailored to the needs of large corporations, including real-time exchange rate updates, automated currency conversion, and integration with treasury management systems. Used this way, a multi-currency account can give a large corporation a single view of its foreign-currency balances, although very large groups often combine it with bank treasury services.
In addition to businesses, freelancers and self-employed individuals can also take advantage of multi-currency accounts to manage their expenses and transactions with international customers. Whether you’re a freelance consultant, a digital nomad, or a remote worker, these accounts provide a convenient way to receive payments in different currencies without converting each payment on arrival. Conversion fees still apply when the money is later exchanged, so compare each provider’s rates.
Furthermore, e-commerce sellers and online merchants can leverage multi-currency accounts to facilitate cross-border sales and mitigate foreign exchange risk. With the rise of global e-commerce platforms and marketplaces, sellers can expand their reach to international customers and accept payments in multiple currencies, thereby enhancing their competitiveness and revenue potential.
In summary, multi-currency business accounts are accessible to a diverse range of entities operating in today’s globalized economy. Whether you’re a startup, a medium-sized enterprise, a large corporation, a freelancer, or an online seller, these accounts can be useful, provided the business meets the provider’s eligibility rules and the fees suit its payment volumes. By opening a multi-currency account, businesses and individuals alike can unlock new opportunities, streamline financial operations, and stay ahead in an increasingly interconnected world.
What Is a Multi-Currency Business Account?
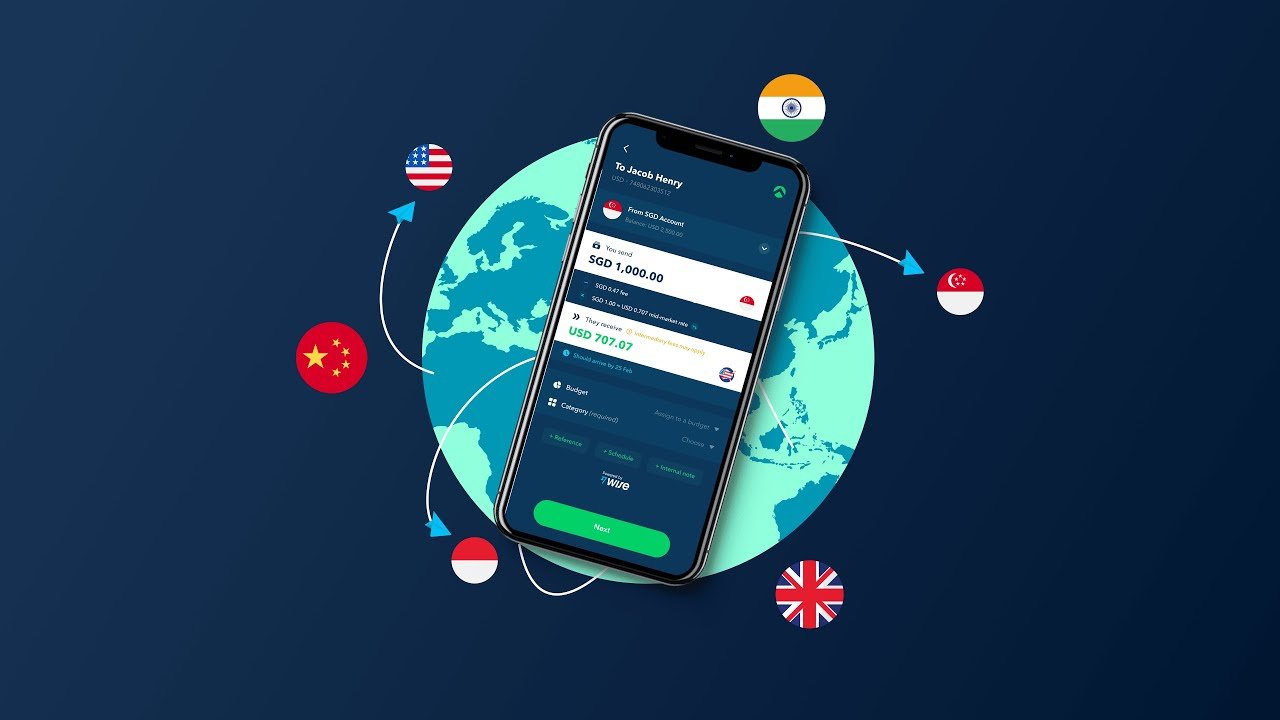
A multi-currency business account is a business account that holds balances in several currencies at once and can receive and send payments in those currencies. Many providers also issue local account details, such as a US account and routing number or a UK sort code, so overseas customers can pay as if they were paying a domestic supplier.
Coverage differs by provider. As of September 2026, Wise says its business account can receive payments in 22 currencies, while Airwallex says its business account can receive funds in 20+ currencies and send transfers in 60+ currencies.
Who Is Eligible for a Multi-Currency Business Account?
Eligibility for a multi-currency business account rests on four tests: the business type, the country where it is registered, the industry it works in, and whether its people pass identity checks. Wise states that eligibility is not based only on entity type, and that business activity, account purpose and its acceptable-use policy may also be reviewed.
Business types commonly accepted
Wise lists the following as supported business types, as of September 2026:
- Sole traders and freelancers
- Limited and public companies
- Partnerships (some UK exceptions apply)
- Trusts registered in Australia, Canada, New Zealand and the United States
Business types and industries commonly refused
Wise says it does not support businesses involved in cryptocurrency, tobacco, adult content or other prohibited activities, businesses with bearer shares in any jurisdiction, Australian superannuation funds and self-managed superannuation funds, or businesses offering goods or services relating to Cuba with US relations. In the UK, Wise does not currently accept trusts, Scottish Limited Partnerships, English Limited Partnerships or Northern Ireland Limited Partnerships.
Other providers draw the lines differently, so a refusal from one provider does not mean every provider will refuse the business. Check the provider’s own list of supported entities and prohibited industries before applying.
What Documents Do You Need to Open a Multi-Currency Business Account?
Providers of multi-currency business accounts must verify both the business and the people behind it. In the US, the Financial Crimes Enforcement Network (FinCEN) customer due diligence rule requires covered financial institutions to identify and verify any individual who owns 25 percent or more of a legal entity customer, plus an individual who controls it.
Wise’s published requirements show what this looks like in practice:
| Requirement | US business (Wise) | UK business (Wise) |
|---|---|---|
| Business identity | Legal entity name, registered address and a physical trading address (not a PO box) | Business name, entity type, registration number, sector, and registered and trading addresses |
| Tax ID | EIN; SSN or TIN for sole proprietors | Not listed in Wise’s UK requirements summary |
| Owners and managers | Every ultimate beneficial owner with 25% or more: full name, date of birth, residential address, email and job title | Information about the company’s directors |
| Personal ID | SSN for US-resident or US-passport owners; photo ID for non-US owners | Photo ID and proof of address for the account representative |
| Other | Website, business description and intended use of the account | Sole traders: photo ID, proof of business address, nature of the business and sometimes a website |
How to Open a Multi-Currency Business Account
- Confirm your structure and country are supported. Check the provider’s list of accepted entity types, registration countries and prohibited industries.
- Gather company documents. Have your registration details, tax ID and business addresses ready.
- List your beneficial owners. Identify everyone who owns 25% or more, and the person who controls the business.
- Prepare personal ID. Each owner or representative may need photo ID and proof of address.
- Describe the business accurately. Providers ask what the business does and how it will use the account; unclear answers slow verification.
- Pay any setup fee and wait for verification. Wise says verification times vary by business type and the information provided; Airwallex says an account can be opened in 1-3 business days.
How Much Does a Multi-Currency Business Account Cost?
Costs for multi-currency business accounts range from free plans to monthly subscriptions, plus conversion and transfer fees. The figures below are as of September 2026 and come from the providers’ own pages; check current pricing before applying.
| Provider | Setup or plan cost | Receiving currencies |
|---|---|---|
| Wise (US) | Free to sign up, no monthly fee or minimum balance; one-time 31 USD fee to receive payments | 22 currencies |
| Wise (UK) | Free Essential plan without receiving features; one-time £50 fee for all features | 22 currencies |
| Airwallex (US) | Explore plan free; Grow plan $99 a month | 20+ currencies |
To estimate what currency conversion itself costs, see this guide on how much foreign currency exchange costs, and this comparison of OFX vs Wise for international transfers.
Common Reasons Applications Are Refused
- The business is registered in a country the provider does not serve.
- The legal structure is not supported, such as a UK trust or Scottish Limited Partnership at Wise.
- The business works in a restricted industry, such as cryptocurrency or adult content at Wise.
- The company has bearer shares, which Wise refuses in every jurisdiction.
- Beneficial owner details or ID documents are missing or incomplete.
Freelancers who invoice overseas clients can pair an account with a free invoice generator so each invoice shows the right currency and payment details. LLC owners weighing other financing needs may also find this guide on how LLCs access funding through business loans useful.
Frequently Asked Questions
Can a sole trader open a multi-currency business account?
Yes, with many providers. Wise lists sole traders and freelancers as supported business types, but not every provider accepts sole traders, so check before applying.
Can a non-resident open a multi-currency business account?
Often, yes. Wise says beneficial owners who are not US residents can supply a copy of a photo ID instead of an SSN for a US business account, but the business itself must meet the provider’s eligibility rules.
Why do providers ask about owners with 25% or more?
Providers ask because of anti-money-laundering rules. In the US, the FinCEN customer due diligence rule requires financial institutions to identify and verify anyone who owns 25 percent or more of a legal entity customer, and a person who controls it.
Is a multi-currency business account free?
Some are free to open, but fees usually apply somewhere. As of September 2026, Wise charges US businesses a one-time 31 USD fee to receive payments and UK businesses a one-time £50 fee for all features, and conversion fees apply when money is exchanged.
Which industries cannot open a multi-currency business account?
It depends on the provider. Wise, for example, does not support businesses involved in cryptocurrency, tobacco or adult content, or businesses with bearer shares.